Oklahoma City health insurance agent · 13+ years · 31 states

Stop overpaying for health insurance. See every plan you qualify for in one free call.

2027 premiums are climbing, and if you earn too much for a subsidy you pay full price. Chris Downham, a licensed agent based in Oklahoma City, compares every plan available in your county, on and off the ACA Marketplace, so you can choose coverage that fits your doctors, prescriptions, and budget. The review is free, and it may save you real money.

Your free plan review

  • ✓About 30 minutes by phone
  • ✓ACA and private plan options side by side
  • ✓Subsidy and 2027 Open Enrollment check
  • ✓No cost and no obligation

Services

Coverage options we help you compare

One conversation covers the plans you are eligible for, explained in plain language.

Individual & Family Health

Coverage for just you or the whole household, chosen around your doctors, prescriptions, and budget.

ACA Marketplace Plans

Enrollment help and subsidy eligibility review, especially valuable when affordability or pre-existing conditions are a concern.

Private, Non-ACA Plans

Alternatives for self-employed people, small business owners, and families who earn too much for subsidies, available in most areas, including outside Open Enrollment.

Dental & Vision

Stand-alone or bundled dental and vision coverage to round out your health plan.

Life Insurance

Straightforward life coverage to protect the people who depend on you.

Small Business Owners

Guidance for owners who need practical coverage for themselves and their families.

Family relaxing together at home after finding affordable health coverage
For individuals & familiesCoverage built around your doctors, prescriptions, and budget.
Small business owner in her shop
For small business ownersPractical options when you earn too much for subsidies.

We do not recommend health sharing ministries or short-term plans as a substitute for real insurance. Our goal is coverage that pays when you need it.

Why work with an agent

Expert help at no cost to you

Insurance companies pay the agent directly, so you get personal guidance without paying a fee or a higher premium.

Chris's licenses allow him to show and explain every plan available in your county, so you can see the full picture before deciding, instead of being steered toward a single option.

Licensed health insurance agent on a phone plan review
A real person on the phonePlan reviews by phone or video, typically about 30 minutes.
  1. ReviewWhat your current or renewal plan really costs: premium, deductible, and out-of-pocket maximum.
  2. CompareACA and private options side by side, matched to your doctors and prescriptions.
  3. EnrollHelp completing enrollment before the deadline, and support after you're covered.

Where we serve

Licensed in 31 states

Headquartered in Oklahoma City and serving clients by phone and video across the Mountain West, Plains, Midwest, South, and Mid-Atlantic.

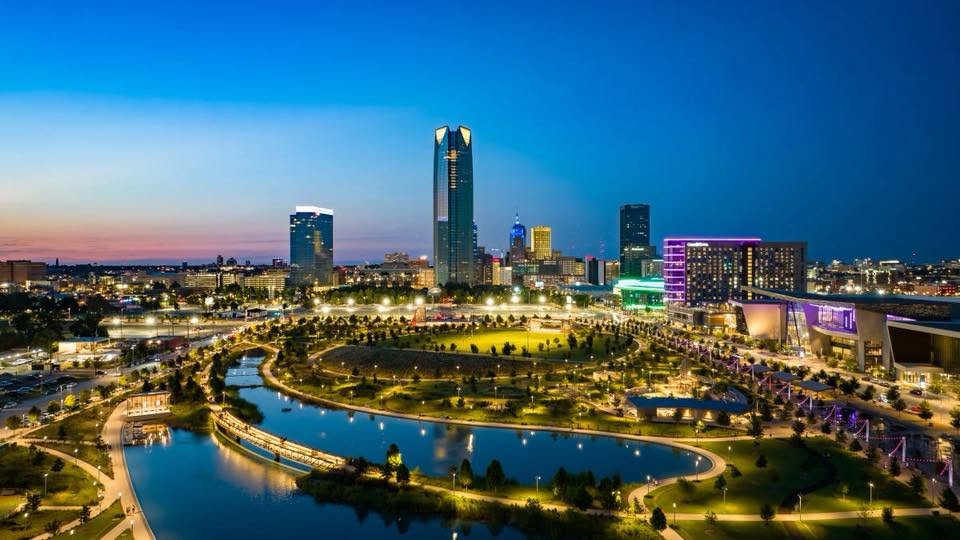
Scissortail Park and Devon Tower in Oklahoma City at dusk
Headquartered in Oklahoma City5909 NW Expressway, Suite 410
MTWYNVUTCOSDNEKSOKTXIAMOARLAWIILMIINOHKYTNMSALGAFLSCNCVAWVMDDE
Mountain West

Montana, Wyoming, Nevada, Utah, Colorado

Plains & Texas

South Dakota, Nebraska, Kansas, Oklahoma, Texas, Iowa, Missouri

Great Lakes & Midwest

Wisconsin, Illinois, Michigan, Indiana, Ohio

Mid-Atlantic

Virginia, West Virginia, Maryland, Delaware

South

Arkansas, Louisiana, Kentucky, Tennessee, Mississippi, Alabama, Georgia, Florida, South Carolina, North Carolina

Coverage map

Hover or tap a state to check licensing status.

Map of U.S. states where Chris Downham is licensed to sell health insurance Alabama Alaska Arizona Arkansas California Colorado Connecticut Delaware Florida Georgia Hawaii Idaho Illinois Indiana Iowa Kansas Kentucky Louisiana Maine Maryland Massachusetts Michigan Minnesota Mississippi Missouri Montana Nebraska Nevada New Hampshire New Jersey New Mexico New York North Carolina North Dakota Ohio Oklahoma Oregon Pennsylvania Rhode Island South Carolina South Dakota Tennessee Texas Utah Vermont Virginia Washington West Virginia Wisconsin Wyoming District of Columbia
LicensedNot licensed
Poster-style illustrated portrait of Chris Downham, licensed health insurance agent

About Chris

Chris Downham, Licensed Health Insurance Agent

For more than 13 years, Chris has helped people on and off ACA plans find coverage that makes sense. He specializes in clients who don't fit neatly into the ACA box, often because their income is too high for subsidies, while still enrolling clients in Marketplace plans whenever those are the better fit.

His approach is simple: explain every option honestly, avoid products that are likely to leave you without coverage, and be there when you actually need to use your plan.

Schedule a Call with ChrisIllustrated portrait of Chris DownhamAlso see our campaign siteObamacareSucks.com: 2027 rate facts, deadlines, and a little humor →

Free guides

Answers before you enroll

Straight talk on the questions people ask Chris most during Open Enrollment.

Oklahoma City health insurance agent

What a local, licensed agent does for you, what it costs (nothing), and what 2027 looks like in Oklahoma.

Self-employed health insurance

Marketplace vs. private plans, estimating income, HSAs, and the self-employed premium deduction.

The 2027 subsidy cliff

Earn $1 over 400% of the poverty level and the subsidy disappears. See the income limits by household size.

FAQ

Frequently asked questions

How much does it cost to work with Chris?

Nothing. Agents are compensated by the insurance companies, so a plan review, quote, and enrollment carry no fee for you, and your premium is the same as buying direct.

Are you a health insurance agent in Oklahoma City?

Yes. The Downham Agency is headquartered at 5909 NW Expressway, Suite 410, Oklahoma City, OK 73132, and Chris helps clients by phone and video across the 31 states where he is licensed. More about working with an Oklahoma City agent.

When is 2027 Open Enrollment?

On HealthCare.gov, Open Enrollment runs November 1, 2026 through January 15, 2027. Enroll by December 15, 2026 for coverage starting January 1; enroll December 16 through January 15 for coverage starting February 1 (HealthCare.gov). Some state-run exchanges set different dates. Outside Open Enrollment, private options may still be available in many areas.

What if I make too much money to get a subsidy?

For 2027, federal premium tax credits are generally limited to households earning 100% to 400% of the federal poverty level, about $63,840 for a single person or $132,000 for a family of four (KFF). Above that line you pay the full premium, which is exactly where Chris spends a lot of his time: comparing full-price Marketplace plans against private options that may cost less for your situation.

How much are health insurance premiums going up in 2027?

It varies by state, county, age, and plan. KFF reports insurers sought a median premium increase of about 15% for 2027 (KFF), and healthinsurance.org reports Oklahoma's average ACA rate increase is 20.1% (healthinsurance.org). A plan review shows what your own renewal really costs.

Why do premiums keep rising, even if I'm healthy?

Individual health insurance pricing is largely set by the overall health and cost of care in your county and rating area, not your personal medical history. Subsidy structures also shift costs onto households that do not qualify for assistance, which is why many people see increases regardless of their own health.

What is the difference between an ACA plan and a non-ACA plan?

ACA (Marketplace) plans are standardized, guarantee coverage for pre-existing conditions, and may qualify for income-based subsidies. Private, non-ACA plans may use medical underwriting and can be a fit for some people who earn too much for subsidies. Chris reviews both and recommends whichever actually fits your situation.

Are there alternatives to an ACA plan?

Depending on your state, health, and income, private non-ACA plans may be available and may cost less than an unsubsidized Marketplace plan. They can use medical underwriting, so they are not right for everyone. Chris will show you both side by side and tell you plainly which one he would pick in your shoes.

I'm self-employed. What are my health insurance options?

Self-employed people can usually choose between Marketplace plans (with subsidies based on household income), private non-ACA plans, and HSA-eligible plans. You may also be able to deduct premiums on your taxes. Read the self-employed health insurance guide.

I rarely see a doctor. Do I really need coverage?

Routine visits and generic prescriptions are often affordable out of pocket. Insurance exists for the major events: a serious diagnosis, surgery, or specialist care after an emergency. Coverage is generally easier and less expensive to secure while you are healthy.

Can I lower what I pay out of pocket for everyday care?

Often, yes. Many plans pay little until a high deductible is met. Some lesser-known plan designs help with common services up front. Chris will walk through how each option handles the care you actually use.

Do you offer health sharing ministries or short-term plans?

Chris generally does not recommend them. These arrangements are not insurance and may limit or deny claims under their terms. The focus is on real coverage that is there when you need it.
Contact

Let's review your options

Book a free plan review online, or reach Chris directly by phone or email.

Book a Free Plan Review
Office
5909 NW Expressway, Suite 410
Oklahoma City, OK 73132
Phone
405-778-9211
Email
downhamagency@gmail.com
Hours
Mon–Thu 8am–8pm
Fri 8am–6pm
Sat by appointment